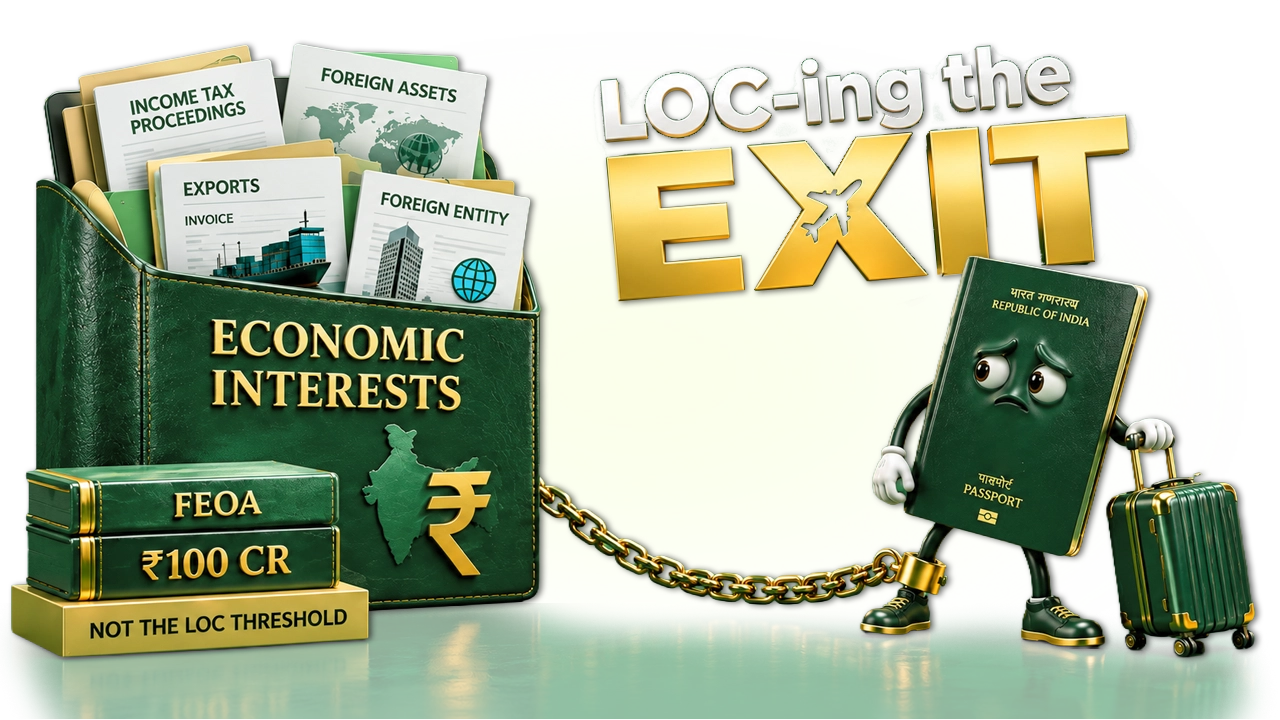
The power to restrict an individual’s travel abroad lies at the intersection of the right to travel and the State’s interest in safeguarding the country’s economic interests. In Income Tax Department v. Vikas Chaudhary & Ors.1 The Delhi High Court examined this balance in the context of a Look Out Circular (“LOC”) issued against an assessee during income-tax proceedings involving allegations of undisclosed foreign assets and interests, over-invoiced exports, fictitious purchases, export incentives and hawala transactions.
Vikas Chaudhary was a director of Nautilus Metal Crafts Pvt. Ltd. and Aastha Apparels Pvt. Ltd., companies engaged in garment exports. Following search proceedings under Section 132 of the Income Tax Act2, Certain goods and documents were seized, and statements of Chaudhary and his wife were recorded. A subsequent search of his locker resulted in the seizure of jewellery valued at approximately ₹1 crore.
At the instance of the Income Tax Department, the Ministry of Home Affairs issued an LOC against Chaudhary. The Department cited, among other things, alleged undisclosed foreign assets and interests in foreign entities, which could attract proceedings under the Income Tax Act, the Black Money Act and the Prevention of Money Laundering Act, 2002 (“PMLA”). Chaudhary challenged the LOC before the Delhi High Court.
The Single Judge quashed the LOC, holding that the material relied upon did not justify its continuation under the provision permitting an LOC in exceptional cases where a person’s departure could be detrimental to the economic interests of India. The Income Tax Department challenged this decision before the Division Bench.
The Division Bench considered the Office Memoranda issued by the Ministry of Home Affairs governing LOCs. While the framework principally contemplated LOCs in cases involving cognizable offences, an amendment dated 05/12/2017 expanded its scope by permitting, in exceptional cases, the issuance of an LOC where the departure of a person could be detrimental to, among other interests, the economic interests of India.
The Court clarified the scope of judicial review applicable to such a decision. It did not treat LOCs as immune from judicial scrutiny. However, it held that judicial review does not ordinarily permit the Court to independently assess the sufficiency or magnitude of the material on the basis of which the competent authority has formed its satisfaction.
The distinction is important. The Court’s role is not to substitute its own assessment of the evidence for that of the executive authority. Judicial intervention may nevertheless be warranted where there is no relevant material, where the material is merely speculative or “moonshine”, or where the decision is otherwise liable to interference on established grounds of judicial review.
The Revenue also relied upon Section 2(m) of the Fugitive Economic Offenders Act, 2018 (“FEOA”)3, which defines a “scheduled offence” by reference to offences specified in the Schedule where the total value involved is ₹100 crore or more. The Department relied on this provision to underscore the magnitude at which certain economic offences are treated as having serious statutory consequences. It further referred to allegations that the respondent was involved in tax evasion exceeding ₹1,500 crore.
The FEOA threshold, however, was part of the Revenue’s submissions and was not adopted by the Court as an independent threshold for issuing an LOC. Similarly, the figure of ₹1,500 crore remained an allegation advanced by the Department and was not a finding by the Court that Chaudhary had, in fact, evaded tax to that extent.
The Department’s counter-affidavit referred to alleged over-invoicing of exports, trade-based money laundering, fictitious purchases, fraudulent availment of export incentives and duty drawback, and alleged hawala transactions. It placed the alleged fraudulent export incentives at approximately ₹170 crore and the alleged fictitious purchases at approximately ₹1,153 crore. The Department also referred to material concerning an alleged acquisition of shares in Centurion International Limited, a Dubai-based company, and to information sought from authorities in Dubai through the Foreign Tax and Tax Research mechanism.
The respondent, on the other hand, relied upon subsequent assessment orders dated 05/07/2021, under which additional undisclosed income was assessed at approximately ₹21.4 crore. These competing figures formed part of the parties’ respective submissions. The Division Bench did not undertake an adjudication of the underlying tax allegations.
Instead, the Court examined the official file produced before it in sealed covers and found that its contents supported the assertions contained in the Department’s counter-affidavit. In these circumstances, the Court held that the decision to restrict the respondent’s departure could not be characterised as being based on irrelevant, inadmissible or insubstantial material.
The Division Bench therefore rejected the basis on which the Single Judge had interfered with the LOC. It held that the question was not whether the Court itself considered the material sufficient, but whether the competent authority had relevant material before it on which the requisite satisfaction could be formed. Finding that such material existed, the Division Bench allowed the Income Tax Department’s appeal and set aside the Single Judge’s judgment, without an order as to costs.
The judgment consequently draws an important distinction between judicial review of an LOC and judicial reassessment of the material underlying it. The former remains available; the latter is ordinarily outside the Court’s remit where the executive decision is supported by relevant material. The Court’s intervention is directed towards the legality and basis of the decision, rather than a re-evaluation of the evidentiary weight assigned by the competent authority.
The judgment also places the Revenue’s reliance on the FEOA in its proper context. The statutory ₹100 crore threshold for a “scheduled offence” under the FEOA does not become a threshold for issuing an LOC on the ground of potential prejudice to India’s economic interests. Likewise, the Court’s decision to sustain the LOC should not be read as a determination that the allegations of ₹1,500 crore in tax evasion were established.
Ultimately, the decision rests on a narrower proposition: where the competent authority has relevant material supporting its satisfaction that a person’s departure may be detrimental to India’s economic interests, the Court will ordinarily not substitute its own assessment of the sufficiency of that material. At the same time, the continuation of an LOC at the judicial-review stage does not amount to a finding of tax liability, wrongdoing or guilt in the underlying proceedings. The judgment therefore reinforces the distinction between examining the legality of executive satisfaction and adjudicating the merits of the allegations that led to it.
Citations
Expositor(s): Adv. Vatsala Pandit