The Gujarat High Court, in Torrent Power Ltd. v. Union of India & Ors1., has examined the GST treatment and valuation of corporate guarantees furnished between related persons. The judgment arose from a batch of thirteen writ petitions challenging, inter alia, Rule 28(2) of the Central Goods and Services Tax Rules, 20172 (“CGST Rules”), Section 15(4) of the Central Goods and Services Tax Act, 2017 (“CGST Act”)3, and CBIC circulars concerning corporate guarantees.
The Court upheld the validity of Rule 28(2) and Section 15(4), but read down the expression “whichever is higher” in Rule 28(2). It further held that GST under Rule 28(2) could not be levied on corporate guarantees furnished before 26 October 2023, although the levy would apply from that date where such guarantees continued. The Court also quashed the Section 744 proceedings challenged before it.
The petitions were filed by entities that had furnished corporate guarantees, including guarantees provided by holding companies for the benefit of subsidiaries and other related entities. The principal challenge concerned Rule 28(2), which provides a specific valuation mechanism for corporate guarantees furnished between related persons. The provision prescribed the value as 1% of the amount of the guarantee offered per annum or the actual consideration, whichever is higher.
The petitioners contended that a corporate guarantee furnished without consideration did not constitute a taxable supply and that Rule 28(2) could not independently create a charging provision. They also challenged the application of the valuation mechanism to guarantees furnished before the rule was introduced.
Corporate Guarantees as Supply
The Court rejected the challenge to the taxability of corporate guarantees between related persons. It examined Section 7 of the CGST Act along with Schedule I, particularly Entry 2, which covers supplies of goods or services between related persons when made in the course or furtherance of business, even without consideration.
The Court held that the statutory framework permits the furnishing of a corporate guarantee between related persons to be treated as a supply of service. Accordingly, the absence of separate consideration did not, by itself, exclude such a transaction from the GST framework.
In reaching this conclusion, the Court also considered the Bombay High Court’s decision in D.P. Jain & Co. Infrastructure Pvt. Ltd. v. Union of India & Ors5. and the Supreme Court’s decision in Edelweiss Financial Services Ltd.6 The Gujarat High Court distinguished Edelweiss on the basis that it concerned the erstwhile service tax regime and its statutory requirement of consideration.
Validity of Rule 28(2) and Section 15(4)
The Court upheld Section 15(4) of the CGST Act and Rule 28(2) as falling within the statutory valuation framework. However, the Court separately examined the constitutional validity of the words “whichever is higher” in Rule 28(2).
The Court noted that the cases before it included instances where the actual commission or charge for corporate guarantees was between 0.25% and 0.3%. It found that mandatorily requiring taxpayers to adopt the higher figure could result in a valuation disconnected from the actual consideration involved.
The Court therefore held the expression “whichever is higher” to be arbitrary and violative of Articles 14 and 19(1)(g) of the Constitution.
Importantly, the Court did not strike down Rule 28(2) in its entirety. Instead, it applied the principle of reading down and removed the mandatory operation of the expression “whichever is higher”. The remainder of the valuation mechanism was preserved.
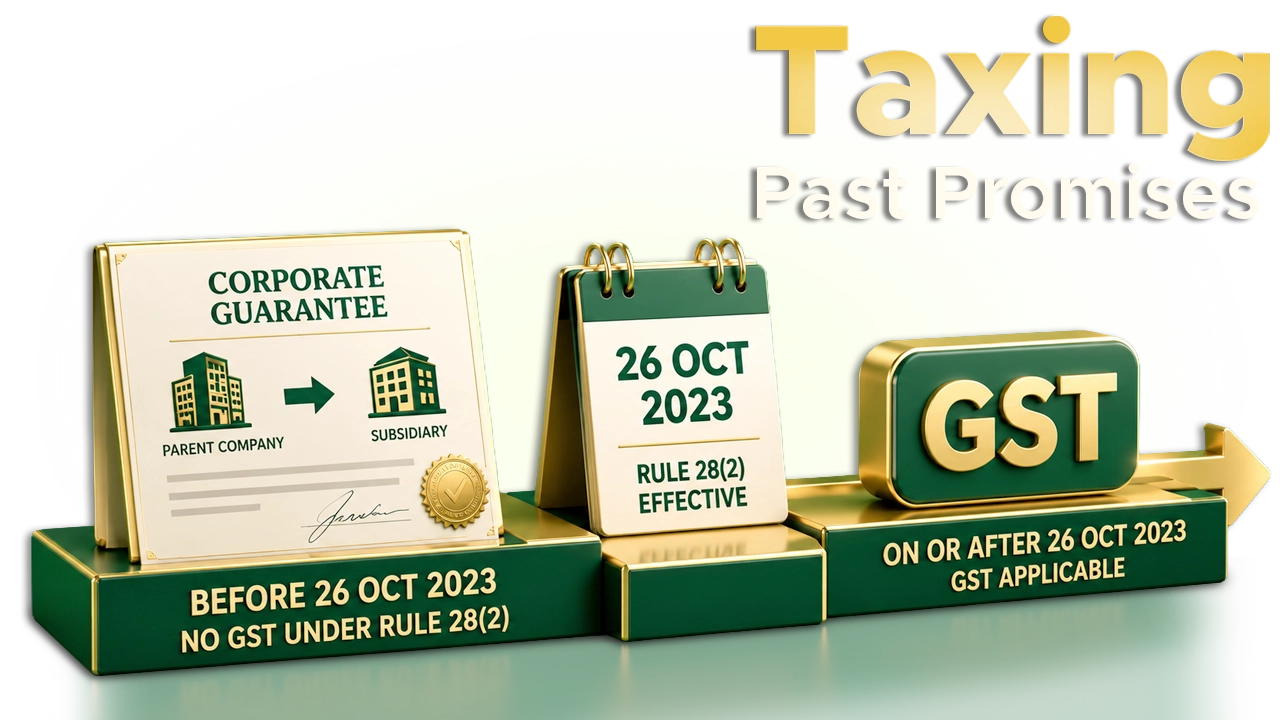
The Court also considered whether Rule 28(2), introduced with effect from 26 October 2023, could be applied to corporate guarantees furnished before that date. The Court held that applying the 1% valuation under Rule 28(2) to guarantees executed before its introduction would operate retroactively. It found that imposing such a levy for a period when the relevant valuation mechanism did not exist would be harsh and unfair to taxpayers who had arranged their financial affairs under the prevailing legal framework.
The Court consequently declared the levy of GST under Rule 28(2) on corporate guarantees furnished before 26 October 2023 to be violative of Articles 14 and 19(1)(g). However, the Court expressly clarified that where such guarantees continued beyond 26 October 2023, the levy would be attracted from that date, since the Court had treated the taxable event as occurring annually.
The Court also examined proceedings initiated under Section 74 of the CGST Act. Section 74 applies where tax has not been paid or has been short-paid by reason of fraud, wilful misstatement or suppression of facts with intent to evade tax.
The Court observed that the petitioners had taken the position that GST was not payable because no consideration was involved in the corporate guarantees. The issue therefore involved a disputed interpretation of the statutory provisions. Relying on Supreme Court precedent, the Court held that mere non-payment or non-declaration does not, by itself, establish wilful suppression. There must be circumstances demonstrating the requisite intention to evade tax. The Court nevertheless clarified that legal complexity cannot automatically be used as an excuse for non-payment. On the facts before it, the Court found no intention to evade tax and held the invocation of Section 74 to be unsustainable. The impugned orders and show-cause notices were consequently quashed.
The Court ultimately held that Rule 28(2) is intra vires, subject to reading down the expression “whichever is higher”; GST under Rule 28(2) on corporate guarantees furnished before 26 October 2023 is impermissible, although the levy applies from that date where such guarantees continue; and Section 15(4) is valid. The Court further quashed the Section 74 proceedings challenged before it and directed that any excess GST deposited be refunded, subject to adjustment if the parties so choose. It also set aside the relevant CBIC circulars to the extent they were inconsistent with the Court’s directions, while permitting the Revenue to issue fresh instructions consistent with the judgment. The Court directed implementation of its directions within three months.
Conclusion
The Gujarat High Court’s decision in Torrent Power Ltd. preserves the GST framework applicable to corporate guarantees between related persons while placing specific limits on its valuation and temporal operation.
The Court has upheld Rule 28(2) and Section 15(4), but has read down the words “whichever is higher” on constitutional grounds. It has also rejected the application of Rule 28(2) to guarantees furnished before 26 October 2023, while permitting the levy from that date where such guarantees continue.
The judgment further emphasises that proceedings under Section 74 require the statutory elements of fraud, wilful misstatement or suppression to be established and cannot rest merely on a disputed interpretation of the GST provisions. The decision therefore provides significant clarification on how corporate guarantees are to be valued and taxed under the GST regime.
Citation
Expositor(s): Adv. Vatsala pandit