IBC · NCLT Judgement
Leasehold Dues and Statutory Charges: Why Statutory Clauses Fail to Create a ‘Security Interest’ Under IBC
On this page
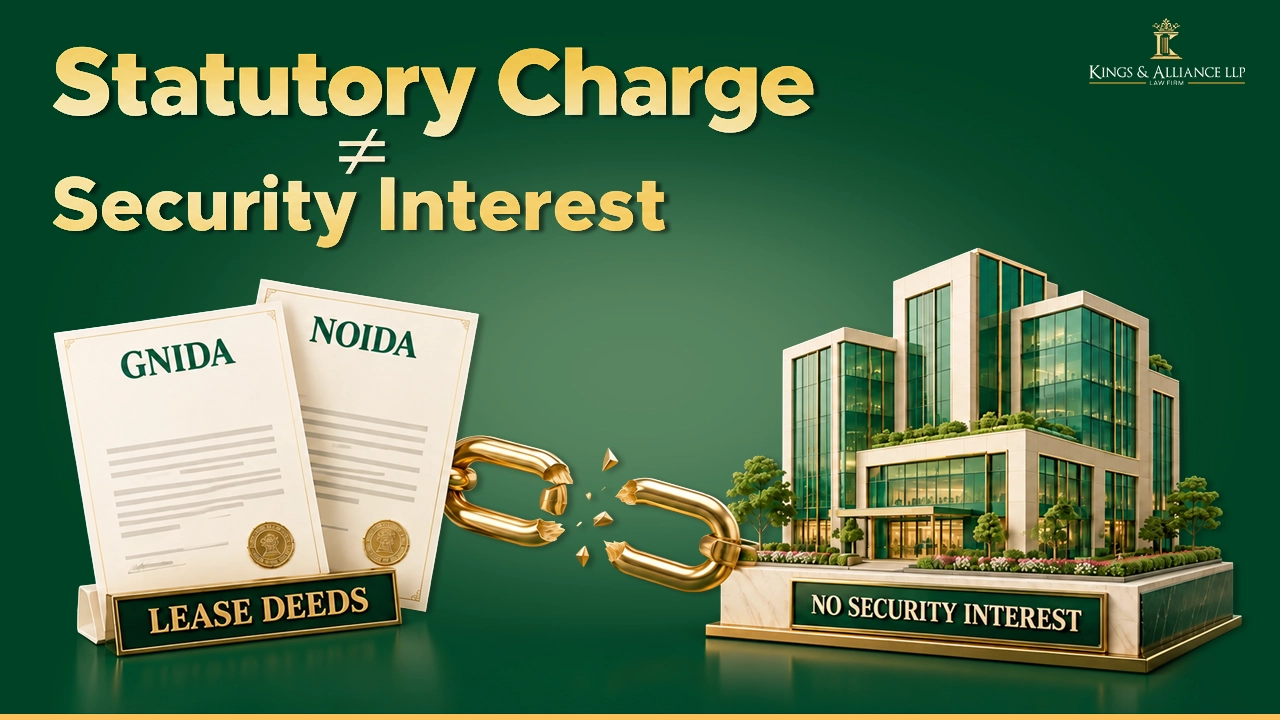
A creditor’s standing as secured versus an operational creditor fundamentally shapes its entitlement under the Corporate Insolvency Resolution Process (CIRP). This was highlighted in Greater Noida Industrial Development Authority v. Anand Sonbhadra,1 wherein the principal bench of NCLAT dismissed the appeals by Greater Noida Industrial Development Authority (GNIDA) and New Okhla Industrial Development Authority (NOIDA), classifying them as unsecured creditors. The principal bench held that the Explanation to Section 3(31),2 as inserted by the 2026 amendment to the Insolvency and Bankruptcy Code, 2016, excludes a security interest created merely by operation of law, and the statutory-charge route relied upon by GNIDA and NOIDA was no longer available
The judgment arose from two appeals concerning the claims of GNIDA and NOIDA in the CIRP of Shubhkamna Buildtech Pvt. Ltd passed by the NCLT in 2022 (Link). In the first appeal, GNIDA had leased land to the Corporate Debtor for residential development against a total premium of ₹37,38,26,200, payable in instalments. Following defaults in payment, GNIDA issued a demand notice and subsequently obtained a Recovery Certificate dated 20 November 2018 for ₹37,83,48,790 towards its outstanding dues. In the second appeal, NOIDA had allotted a plot measuring 22,565.77 sq. metres to the Corporate Debtor under a 90-year registered lease deed and filed a claim of ₹99,32,55,183 in the CIRP. The initial Resolution Plan proposed payment of ₹41.40 crore towards NOIDA’s claim, which was subsequently reduced to ₹25 crore under the revised Resolution Plan. Both authorities challenged the NCLT’s approval of the Resolution Plan dated 12 September 2022, principally questioning their treatment as unsecured creditors and the reduction of their claims.
GNIDA & NOIDA: Secured or Operational Creditors?
Both authorities advanced a common contention that the outstanding lease premium, lease rent, additional compensation, and other statutory and contractual dues payable to them were secured against the leased properties by virtue of the statutory charge created under the applicable provisions of the Uttar Pradesh Industrial Area Development Act, 1976. On this basis, they contended that they fell within the definition of a “secured creditor” under Sections 3(30)3 and 3(31) of the Code and could not be treated merely as ordinary or unsecured claimants. In support of their contention, both authorities relied on the Supreme Court’s decision in State Tax Officer v. Rainbow Papers Ltd.4, which held that a statutory charge created in favour of a government authority under the applicable statute confers on such authority the status of a secured creditor. The authorities further contended that the same principle had been applied by the Appellate Tribunal in Assets Care & Reconstruction Enterprise Limited v. Mr. Viswanadha Sarma (Resolution Professional of Arena Superstructures Private Limited),5 and that they were consequently entitled to the benefits flowing from their status as secured creditors.
Anand Sonbhadra, the Respondent and Resolution Professional for Shubhkamna Buildtech Pvt. Ltd., contended that the Appellants’ claims arose from allotment and lease-related dues without any express statutory charge over the Corporate Debtor’s assets, and that Section 13-A6 of the U.P. Industrial Area Development Act, 1976 was neither invoked nor enforced during the CIRP. Accordingly, Rainbow Papers was distinguishable, as it involved an express statutory first charge under the Gujarat VAT Act. He further submitted that the Appellants were already classified as operational creditors and were therefore entitled only to the statutory minimum under Section 30(2)(b) read with Section 53 of the Code.
The Successful Resolution Applicant (SRAs), the co-respondents, contended that the Resolution Plan, approved by the CoC with 87.57% votes on 17.10.2019, was compliant with the Code and the prevailing legal position. They submitted that the Appellants had not challenged their classification as unsecured operational creditors before the Adjudicating Authority and raised the secured-creditor claim only in appeal. The Plan provided ₹25 crore towards NOIDA’s dues and ₹18.5 crore towards GNIDA’s dues under statutory/government operational dues. The SRAs further submitted that the recognition of NOIDA as a secured creditor was settled only subsequently in Greater Noida Industrial Development Authority v. Prabhjit Singh Soni7 in 2024, and that allocation among creditor classes was within the CoC’s commercial wisdom.
Lastly, the Homebuyers, representing the CoC, submitted that 95.6% of the participating Homebuyers had rejected the proposal to treat NOIDA and GNIDA as secured operational creditors, with only 4.4% voting in favour. They relied on the Supreme Court’s decision in NOIDA v. Anand Sonbhadra,8 which recognised NOIDA only as an operational creditor. They further contended that treating GNIDA as a secured creditor by operation of law was no longer sustainable in view of the 2026 amendment to the definition of “security interest” under the Code, which expressly excludes security interests arising by operation of law and, being clarificatory, operates retrospectively.
Decoding the Tribunal’s Decision
The Tribunal first analysed the lease deeds and held that they did not create a present and subsisting charge over the leased properties. The “first charge” was limited to the Lessor’s share of the unearned increase in the value of the land and was contingent upon a sale or foreclosure of a mortgage, neither of which had occurred. Further, the Tribunal observed that the recovery of arrears as land revenue under Sections 13 and 13-A of the Uttar Pradesh Industrial Area Development Act, 1976, was a statutory recovery mechanism rather than a charge created by the terms of the lease deeds. It held that any security character attached to this mechanism arose by operation of law and did not, by itself, establish a “security interest” under the Code. Accordingly, the Tribunal rejected GNIDA and NOIDA’s contention that the statutory charge conferred secured-creditor status upon them, notwithstanding their reliance on Prabhjit Singh Soni and Rainbow Papers Ltd. The Tribunal further observed that the ratio in Assets Care rested on a materially different factual foundation, as the lease deeds in that case differed substantially from those in the present case, rendering the decision inapplicable.
Lastly, while classifying both the authorities as unsecured creditors, the Tribunal held that the Explanation to Section 3(31) of the Code, inserted by the IBC (Amendment) Act, 2026 and brought into force on 26.05.2026, now excludes such interests from the definition of “security interest”. The Tribunal further noted that the amendment would have retrospective effect, as clarified in Avenue Realty v. Assistant Commissioner, Srirangam (GST Circle) & Ors.9, which supports the view that an amendment of a clarificatory nature operates retrospectively.
A Charge Is Not Always a Security Interest
The NCLAT ultimately dismissed the appeals filed by GNIDA and NOIDA, holding that the lease deeds and the statutory recovery mechanism under the UPIDA did not create a present security interest capable of conferring secured-creditor status upon the authorities. The Tribunal distinguished Rainbow Papers, Prabhjit Singh Soni and Assets Care on the facts and upheld the treatment of GNIDA and NOIDA as operational creditors under the approved Resolution Plan. The decision underscores that a statutory right to recover dues, by itself, does not necessarily create a “security interest” under the Code, and that the nature of the charge must be examined in the context of the statutory and contractual framework governing the claim.
Citations
- Greater Noida Industrial Development Authority v. Anand Sonbhadra, 2026 SCC OnLine NCLAT 1123 ↩︎
- Insolvency and Bankruptcy Code, 2016, s. 3(31), Explanation, as inserted by the Insolvency and Bankruptcy Code (Amendment) Act, 2026. ↩︎
- Insolvency and Bankruptcy Code, 2016, s. 3(30) ↩︎
- State Tax Officer v. Rainbow Papers Ltd., (2023) 9 SCC 545. ↩︎
- Assets Care & Reconstruction Enterprise Limited v. Viswanadha Sarma & Ors., Company Appeal (AT) (Ins.) No. 949 of 2023, NCLAT, New Delhi ↩︎
- The Uttar Pradesh Industrial Area Development Act, 1976 (U.P. Act No. 6 of 1976), s. 13-A ↩︎
- Greater Noida Industrial Development Authority v. Prabhjit Singh Soni & Anr., (2024) 2 SCR 258. ↩︎
- NOIDA v. Anand Sonbhadra, [2022] 5 S.C.R. 319. ↩︎
- Avenue Realty v. Assistant Commissioner, Srirangam, 2026 SCC OnLine Mad 3739 ↩︎
Expositor(s): Adv. Stephin Sinu Oommen and Adv. Siddharath Shrivastava
This article is for information only and is not legal advice. Read the disclaimer