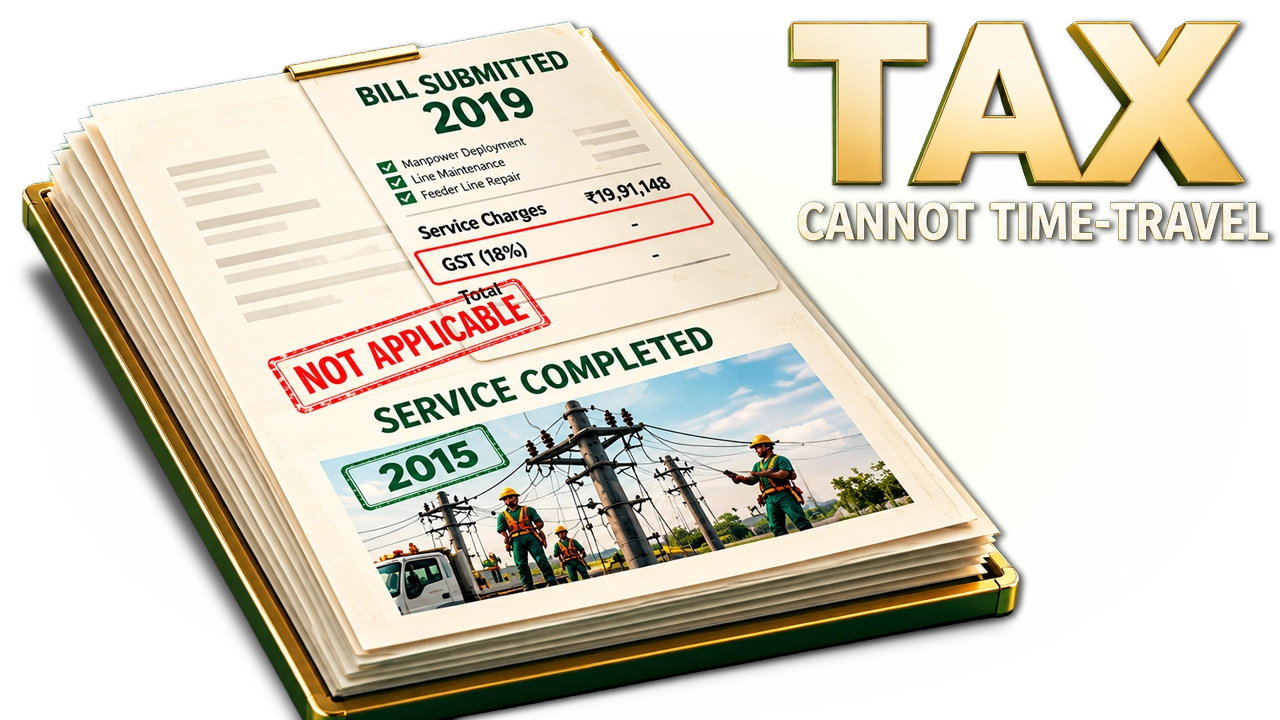
A tax dispute before the Calcutta High Court turned on an evidently simple yet tricky question of law: Can a Service completed before the introduction of the GST regime be subject to GST because the work was post facto approved and billed after the introduction of the GST regime?
M/S Goutam Engineering Concern deployed technical personnel for repairs and maintenance of electric feeder lines between January 1, 2015 and December 31, 2015, originating from Belmuri 33/11 KV Sub-Station. The work received post-facto approval on an order dated February 26, 2018. The Petitioner submits that despite completing the work within the allotted time and submitting the bills, the respondents have not released the amount payable. The respondents relied on the argument that the Petitioner has not completed the requisite formalities for GST registration and has withheld ₹19,91,148. The dispute has reached the High Court.
Facts of the Case
Goutam Engineering Concern was provisionally enlisted as an erection contractor under the Distribution Wing of the West Bengal State Electricity Distribution Company Limited (WBSEDCL), and its work includes deploying technical personnel to repair and maintain electrical lines within its allotted working area in Hooghly.
The Petitioner company was entrusted by WBSEDCL from time to time for various works. The Petitioner always executed them without any complaints or adverse remarks. In 2015, the Petitioner company was asked to deploy technical personnel to repair and maintain feeder lines originating from the Belmuri 33/11 KV Sub-Station1 from January 1, 2015, to December 31, 2015. The work was not formally approved, but it was carried out. WBSEDCL issued an order on February 26, 2018, granting post facto approval for the work. That order also authorised the amount payable to the Petitioner. The Petitioner then submitted twelve monthly bills, each dated October 30, 2018, to the authorities on February 22, 2019. The total amount claimed was: ₹19,91,148. However, WBSEDCL did not release the money. Stating that the Petitioner had not completed the necessary GST formalities and that GST liability arose in respect of the amount claimed. This problem centred on a simple question: whether a Service actually performed in 2015 became subject to GST because its approval and billing occurred after GST came into force on July 1, 2017.
The Dispute
The main dispute arose because there was a reasonable gap between when the work was actually performed in 2015 and when it was formally approved and billed in 2018 and 2019, respectively. The Petitioner subsequently requested the release of the amount payable under the order dated September 22, 2019. Nonetheless, the payment was withheld because the Petitioner had not complied with the required formalities under the West Bengal Goods and Services Tax Act, 2017 (“GST Act”).2 The Petitioner also pointed out that the 2018 approval order itself indicated that no sales tax, VAT or excise duty was leviable on the amount.3
This issue specifically fell between the Service Tax system and the GST regime. GST in West Bengal started on July 1, 2017, but the work had been done in 2015 itself.
Argument from the Petitioner
The Petitioner set forth a four-fold argument that the Service was completed before the GST. Firstly, the entire workforce allocation took place in 2015. Therefore, the taxable event had already occurred before the GST Act came into force. Secondly, the Petitioner also pointed out that post-facto approval does not change the time at which the Service was performed. The Petitioner accepted that the formal approval was granted only on February 26, 2018, but the date of approval cannot transform a 2015 Service into a 2018 Service. Thirdly, the Petitioner stated that GST provisions cannot tax past transactions retrospectively. Lastly, the Petitioner also argued that WBSEDCL could not simply refuse to pay the money by asserting that the taxpayer had not complied with GST formalities, when GST itself did not apply to the transaction.
The Petitioner prays for relief, seeking the release of the amount of ₹19,91,148, together with interest compounding at 12% per annum from September 22, 2019.
Argument from the Respondents
The Respondents replied to the arguments, pointing out that although the work was related to 2015, its post-facto approval was only given on February 26, 2018. The Respondent submitted that the Petitioner had presented the bills only in 2019 and thus had not complied with the applicable GST formalities, and that the amount could not be released without such compliance.
The Respondents also shed light upon a pending dispute with M/s. Aim Light, in relation to a dispute concerning the payment of wages to the labourers. M/s. Aim Light instituted a suit, being T.S. No. 494 of 2021, against the Petitioner company before the competent Civil Court and in which WBSEDCL was also added. The suit was still pending. The respondents were apparently utilising this ongoing litigation as an additional justification for withholding payments.
The Petitioner, however, rebutted that there was no interim order restraining WBSEDCL from making payment to the Petitioner.
The Court’s Reasoning
The Court initially observed that deploying technical personnel constituted a supply of Services, reading Section 2(102) of the GST Act,4 and that the Services had already been rendered well before GST came into force on July 1, 2017.
The Court also referred to Section 142 (11) (b) of the GST Act,5 and Memorandum No. 5050-F(Y) dated August 16, 2017, by the Audit Branch, Finance Department, Government of West Bengal.6 The Court held that the subsequent post-facto approval granted on February 26, 2018, could not alter the date on which the Service was actually supplied: “Granting post facto approval to the work already executed cannot, by itself, alter the date on which the service was actually supplied or bring such completed service within the GST regime.” 7
It was concluded that the submission of the bills in February 2019 could not include a Service completed in 2015 under GST. Hence, the Court ruled that the transaction was covered by the erstwhile Service tax law rather than under the GST Act.
Conclusion
In this case, the Court awarded 8% interest rather than 12%, observing that the dispute over GST liability made the entirety of the delay non-attributable to WBSEDCL, and ordered WBSEDCL to pay an amount of ₹19,91,148 along with 8% interest, subject to applicable pre-GST taxation deductions, within four weeks.
Citation
Expositor(s): Adv. Stephin Sinu Oommen