Case Docket · IBC Insights
When a Debenture Holder Becomes a Related Party: The Supreme Court in ECL Finance
On this page
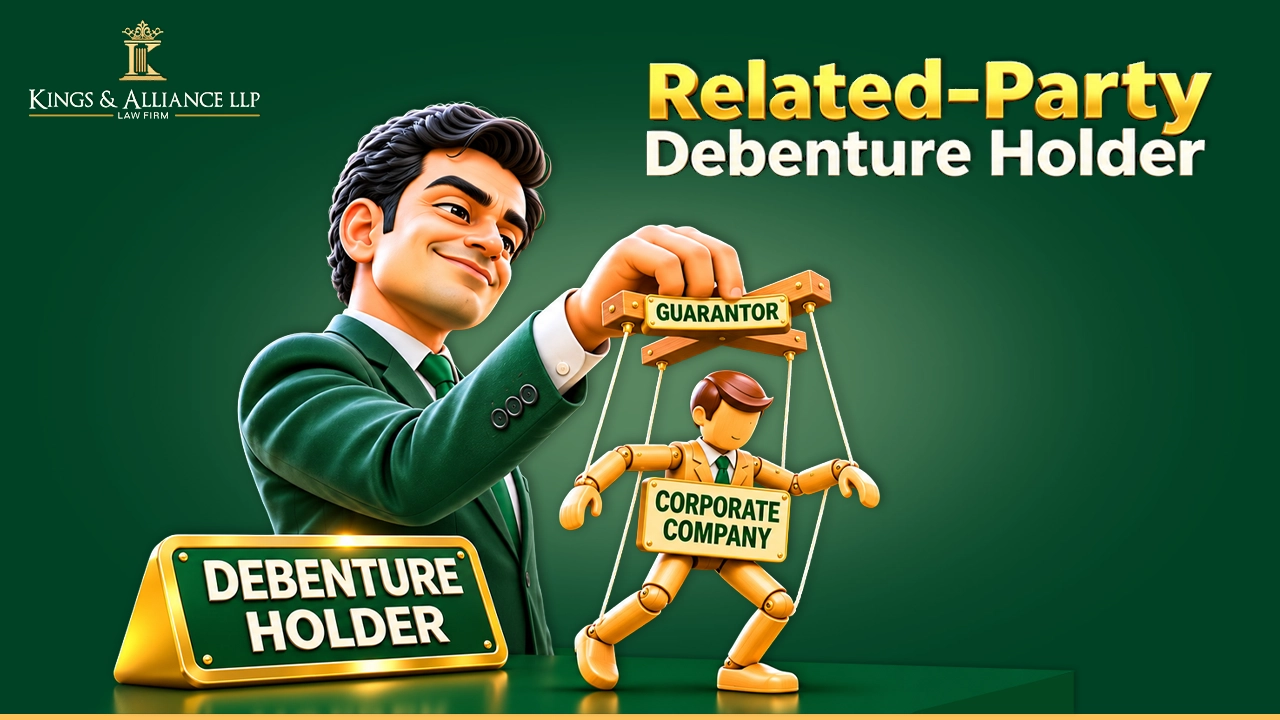
In 2018, the proviso to Section 21(2) was substituted to extend the bar on related-party financial creditors, covering their representation, participation and voting in CoC meetings. But does a financial creditor’s association with the corporate debtor through participation in its policy-making process make it a related party under Section 5(24)(m)(i)1 of the Code? The Supreme Court answered in the affirmative in ECL Finance Ltd. v. Abhinav Mukherjee.2 The Court dismissed the appeals of the Debenture Trustee, IDBI Trusteeship Services Limited (ITSL), and the Debenture Holder/Lender, ECL Finance Limited (ECL), against their exclusion from the Committee of Creditors (CoC). It found ECL to be a related party under Section 5(24)(m)(i) of the Code, exercising all-pervasive control over the projects and management of the corporate debtor, and held that ITSL, which sought to protect ECL’s interest as sole Debenture Holder, was excluded as well.
Saha Infratech Private Limited (SIPL) borrowed funds through two separate financial arrangements with the appellant, ECL. In the first arrangement, SIPL raised ₹110 Crore by issuing debentures (non-convertible) which were entirely subscribed by ECL, with ITSL acting as the Debenture Trustee to oversee the transaction and protect the investor’s rights. In the second arrangement, SIPL availed a direct revolving credit facility of ₹90 Crore directly from ECL. Palm Developers Private Limited (the Corporate Debtor/CD) guaranteed both obligations by an unconditional and irrevocable corporate guarantee, alongside a wider security package that included a first charge and mortgage over Project Encore and a pledge of shares held by the shareholders.
On January 27, 2020, Palm Developers entered the Corporate Insolvency Resolution Process (CIRP). Subsequently, both ITSL and ECL submitted their claims as Financial Creditors for ₹131.17 Crore and ₹139.02 Crore, respectively, and were included in the CoC. However, an individual Homebuyer objected to their inclusion in the CoC. The NCLT accepted his locus and found that the claims were not financial debt, as the CD had incurred no financial debt and no amount was directly disbursed to it. The NCLAT held that the claims could not be entertained because the corporate guarantee had not been invoked before the CIRP. The NCLAT also upheld the individual Homebuyer’s locus to object to ITSL and ECL’s inclusion, and the Supreme Court agreed, relying on Phoenix ARC v. Spade Financial Services.3
The Supreme Court held that the NCLT misread Anuj Jain, Interim Resolution Professional for Jaypee Infratech Ltd. v. Axis Bank Limited and Others,4 in treating a guarantor who is not the principal borrower as owing no financial debt, since the cited decision itself recognizes that financial debt may include ‘any liability in respect of a guarantee or indemnity’. On the NCLAT’s non-invocation ground, the Court held that the NCLAT erred, relying on China Development Bank v. Doha Bank Q.P.S.C.,5 which held that Section 5(8)6 defines financial debt by its nature and does not require a default, and on Phoenix ARC, which the Court treats as answering affirmatively that a guarantee not invoked before the CIRP is still financial debt.
Both the NCLT and NCLAT found that ECL and ITSL were related parties of the Corporate Debtor, thereby disentitling them from participating in the CoC. In arriving at this conclusion, the tribunal examined the terms of the Debenture Trust Deed and the Facility Agreement and relied heavily on the Supreme Court’s ruling in ArcelorMittal India Private Limited v. Satish Kumar Gupta and Others.7 In ArcelorMittal, the Apex Court interpreted the meaning of “control” under Section 29A8 of the Code, establishing that “control” requires positive, proactive authority to drive company policy and management, rather than mere negative or reactive control such as the power to block special resolutions.
However, the Supreme Court in the present case clarified that establishing a “related party” status under Section 5(24)(m)(i) of the Code requires a lower threshold than proving “control” under Section 29A. Unlike Section 29A, which demands full proactive management (“being in the driving seat”), Section 5(24)(m)(i) merely requires participation in policy-making. Thus, a role of navigation in determining policy and channelising business interests suffices to make a financial creditor a related party, barring its representation, participation and voting in the CoC under the first proviso to Section 21(2).
The Court distinguished ECL’s two roles: sole Debenture Holder (all ₹110 Crore of debentures) and Term Loan Lender to SIPL, both guaranteed by the Corporate Debtor. It examined the debenture-holder status first, which falls under Section 21(6A)(a) and so within the first proviso to Section 21(2). On this, it relied on Clause 7.1 of the CD’s Articles of Association, under which any board or shareholder deadlock went to the debenture holders or lenders for a final and binding decision, and on the amended Debenture Trust Deed, under which the Debenture Trustee/Monitoring Agent could approve the quarterly construction budget of the issuer and the security providers. Turning separately to the Facility Agreement and Sanction Letter, it noted ECL’s right to appoint a nominee director on the Borrower’s Board and on the committees of the Borrower and security providers, an observer, a consent right over removal of managerial personnel of the Borrower or Obligor, and the power to appoint sales agents on behalf of the CD.
The Court found “all-pervasive control” that was not “a mere restrictive or negative control,” and rejected the argument that these rights were never exercised, since policy implementation and the business carried out were under ECL’s overall supervision. This met the lower threshold. Although an ordinary financial creditor outside Sections 21(6), 21(6A) and 24(5) would not have been disqualified, ECL’s disability as Debenture Holder under the Debenture Trust Deed carried over to its status as Lender. As ECL held every debenture, ITSL, the Debenture Trustee protecting its interest, was likewise excluded from the CoC. The Court also held that ECL’s recent mid-CIRP assignment of its Facility Agreement rights to the second appellant (the assignee) was not bona fide, given the forensic audit findings of fraudulent fund diversion, and excluded the assignee from the CoC as well.
The Supreme Court corrected the tribunals on the financial debt question but upheld the finding that ITSL and ECL were related parties, dismissed the appeals, closed the contempt petitions, and rejected pending applications, if any..
Citations
- The Insolvency and Bankruptcy Code, 2016, s. 5(24)(m)(i) (India). ↩︎
- ECL Finance Ltd. v. Abhinav Mukherjee, 2026 INSC 1159 ↩︎
- Phoenix ARC Private Limited v. Spade Financial Services Limited, (2021) 3 SCC 475. ↩︎
- Anuj Jain, Interim Resolution Professional for Jaypee Infratech Ltd. v. Axis Bank Ltd., (2020) 8 SCC 401. ↩︎
- China Development Bank v. Doha Bank Q.P.S.C., (2025) 7 SCC 729. ↩︎
- The Insolvency and Bankruptcy Code, 2016, s. 5(8) (India) ↩︎
- ArcelorMittal India Private Ltd. v. Satish Kumar Gupta, (2019) 2 SCC 1 ↩︎
- The Insolvency and Bankruptcy Code, 2016, s. 29A (India) ↩︎
Expositor(s): Adv. Siddharath Shrivastava
This article is for information only and is not legal advice. Read the disclaimer